January 2, 2025
Good morning,
Happy New Year everyone!
On Monday, we wrote about changes that might be in store for markets in 2025. Sentiment changing to extreme bullishness by investors (recall that sentiment is a contra-indicator – bullish sentiment is bearish for equity index prices and vice-versa), yields rising throughout the yield curve while the Fed considers more rate cuts (higher yields are not historically great for equity prices), valuations rising from their already record high levels (no explanation needed) and model portfolios moving to less than overweight equities. None of these changes are bullish. This morning, we’ll look at what history has to say about 2025.
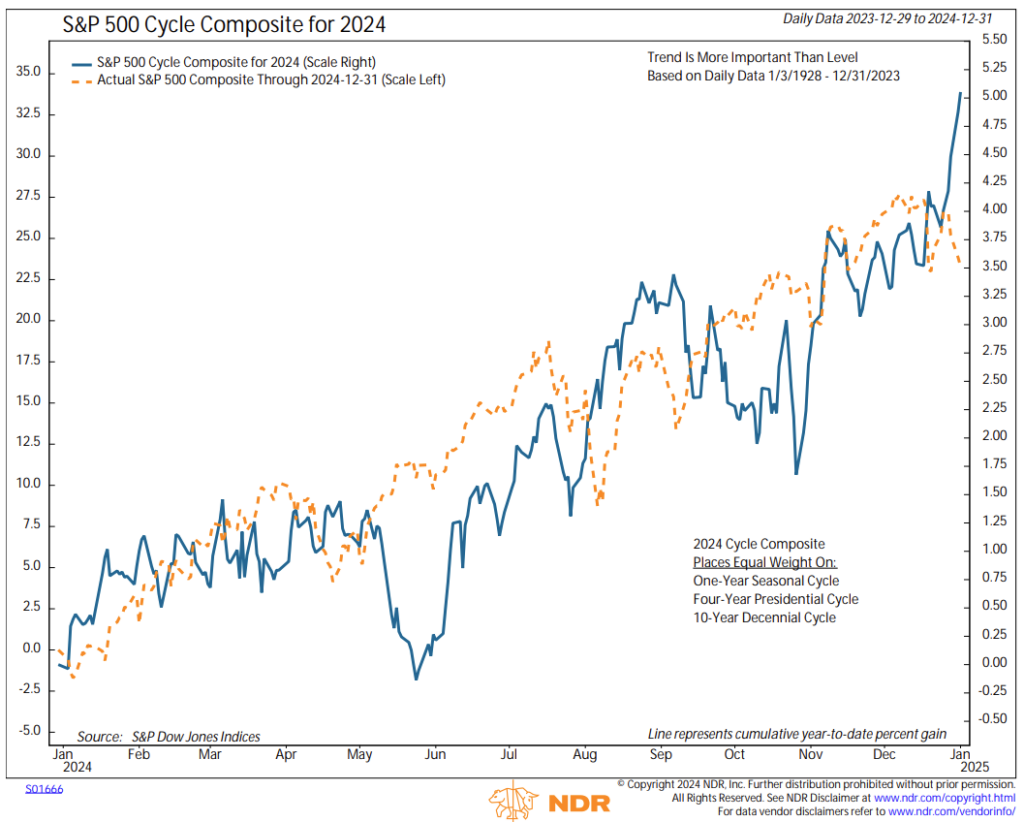
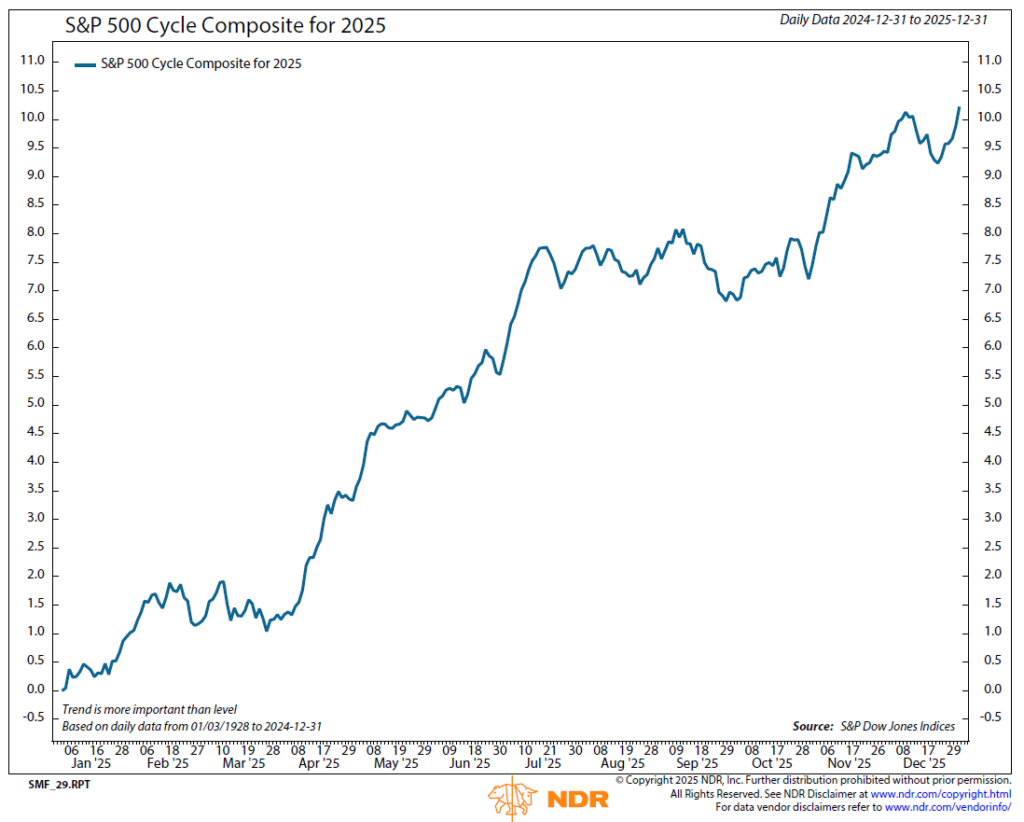
Cycles Composite Charts are a compilation of 1 year, 4 year (election), and 10 year, cycles for the S&P 500 Index. Long term readers of these Morning Notes have been seeing Cycles Composite Charts for years. As a reminder, these charts do not inform any portfolio decisions during the year but are often referenced to have some idea of how history may be influencing markets at any point in time. As you’ll see below, history is a positive offset to the worries listed above.
Note that the direction of the trend is more important when reading the cycle charts than the actual levels. Last year, the market was ahead of the cycle composite curve until December’s correction. For 2025, history suggests that the markets will climb its wall of worry (paragraph 1) to the end.
So, it is not all doom and gloom around here as Monday’s note might have suggested. The bullish message of the market did suffer some damage in December’s correction but remains overweight equities. I would characterize the concerns above (paragraph 1) as reasons to be on high alert. That is likely to be the main market call for Q1-2025 – High Alert, indeed.
Be well,
Mike
Disclosures
Investment advisory services offered through Robertson Stephens (“Robertson Stephens”), an SEC-registered investment advisor. Registration does not imply any specific level of skill or training and does not constitute an endorsement of the firm by the Commission. This material is for general informational purposes only and should not be construed as investment, tax or legal advice. It does not constitute a recommendation or offer to buy or sell any security, has not been tailored to the needs of any specific investor, and should not provide the basis for any investment decision. Please consult with your Advisor prior to making any Investment decisions. The information contained herein was compiled from sources believed to be reliable, but Robertson Stephens does not guarantee its accuracy or completeness. Information, views and opinions are current as of the date of this presentation, are based on the information available at the time, and are subject to change based on market and other conditions. Robertson Stephens assumes no duty to update this information. Unless otherwise noted, any individual opinions presented are those of the author and not necessarily those of Robertson Stephens. Performance may be compared to several indices. Indices are unmanaged and reflect the reinvestment of all income or dividends but do not reflect the deduction of any fees or expenses which would reduce returns. A complete list of Robertson Stephens Investment Office recommendations over the previous 12 months is available upon request. Past performance does not guarantee future results. Forward-looking performance targets or estimates are not guaranteed and may not be achieved. Investing entails risks, including possible loss of principal. Alternative investments are only available to qualified investors and are not suitable for all investors. Alternative investments include risks such as illiquidity, long time horizons, reduced transparency, and significant loss of principal. This material is an investment advisory publication intended for investment advisory clients and prospective clients only. Robertson Stephens only transacts business in states in which it is properly registered or is excluded or exempted from registration. A copy of Robertson Stephens’ current written disclosure brochure filed with the SEC which discusses, among other things, Robertson Stephens’ business practices, services and fees, is available through the SEC’s website at: www.adviserinfo.sec.gov. © 2025 Robertson Stephens. All rights reserved. Robertson Stephens is a registered trademark of Robertson Stephens in the United States and elsewhere.
Robertson Stephens paid no fee to obtain recognition but has paid licensing fees to reference its appearances on the Newsweek, USA Today, and FA Magazine rankings lists. See Awards Disclosures
Questions
How Does Robertson Stephens Manage Investments?
We build personalized portfolios based on your specific situation, including your risk tolerance, tax sensitivity, liquidity needs, and values. We use a disciplined approach that balances long-term growth strategies with short-term opportunities when they make sense. We continuously monitor your investments and adjust as needed, drawing on institutional-quality research and due diligence.
What Is Robertson Stephens’ Investment Philosophy?
Our investment philosophy focuses on protecting and growing your wealth through a disciplined, diversified approach that’s tailored to your specific situation — your risk tolerance, tax needs, and values. We blend long-term strategic investing with tactical opportunities when they make sense, using both public and private markets where appropriate.
Is Robertson Stephens Fee-Only, Fee-Based, or Commission-Based?
We work on a fee-based model, which means our compensation is tied to the assets we manage for you rather than commissions on products we sell. This aligns our interests with yours — when your portfolio grows, we do better too. The specific fee structure varies by client based on your situation and needs.