
The Long Launch: Supporting Adult Children Without Dampening Their Drive
Many parents expect an empty nest after college. Instead, there may be a recent graduate back in the guest room, or living in an apartment still funded by the Bank of Mom and Dad. This phenomenon is surprisingly common. In 2023, 18% of adults ages 25 to 34 were living in a parent’s home, and half of parents with adult children say they provide regular financial assistance to one or more of their kids (Pew Research).
Retiring Abroad? Plan Before You Pack
With the rising cost of living, more families are exploring whether their retirement savings could go further outside the U.S. For some, moving abroad offers a more affordable lifestyle. For others, it provides an opportunity to return to a country where they hold citizenship or have family ties. Understanding how a move may affect taxes, investments, and estate planning is an important part of evaluating that decision.
Second Homes, New Taxes: How Local Governments Are Rewriting the Wealth Planning Map
This summer, those with vacation homes in New York City may have received letters in the mail from the city. Those letters are the first wave of enforcement for a new pied-à-terre surcharge that took effect July 1, 2026. Here’s how it works: if a household owns a home in the city worth $5 million or more and doesn’t use it as a primary residence, the city adds an annual surcharge on top of the regular property tax bill. Condos and co-ops currently trigger the surcharge at a much lower $1 million threshold, not because the policy targets smaller units, but because the city’s valuation method for those properties runs well below true market value; a $1 million “city value” condo may really be worth $5 million on the open market. The rules run for five years before they’re set to expire.
Experts Explain 6 of the Best Assets to Inherit (and Pass on to Loved Ones)

Mallon FitzPatrick, Head of Wealth Planning at Robertson Stephens Wealth Management, LLC, was featured in Money Talks News. Click here to read more.
Private placement life insurance draws ultra-wealthy interest
Mallon FitzPatrick, Head of Wealth Planning at Robertson Stephens Wealth Management, LLC, was featured in InvestmentNews, where he shares his perspective on growing interest in Private Placement Life Insurance (PPLI) and how ultra-high-net-worth families use the strategy for tax-efficient investing and long-term estate planning. Click here to read more.
The Trouble With an All-Pre-Tax Retirement
For years, the standard retirement advice was simple: max out your traditional 401(k), take the upfront deduction, and let Uncle Sam wait to tax your Required Minimum Distributions (RMDs) in retirement. Watching your taxable income shrink on your W-2 can feel like an immediate win. But if you follow this path for decades, you may arrive at retirement with a less welcome discovery: a portfolio that is almost entirely pre-tax is not a nest egg so much as an income tax bill in waiting. On top of that, if your heirs are non-spouses, they’ll likely face the 10-year distribution rule on any pre-tax IRA they inherit, often during their own high-earning years.
Opportunity Zone Deadline Approaches: Is Your Tax Plan Ready?
For taxpayers with Opportunity Zone investments under the original program, the deferral window closes on December 31. Any capital gain deferred into a Qualified Opportunity Fund must be recognized as income this year, regardless of whether the investment has been sold or produced any cash to cover the tax. That gap between when the gain is taxed and when cash is actually on hand can create a liquidity crunch, and it’s worth getting ahead of before year-end.
PPLI: The Current Hot Topic for the Ultra-Wealthy
The Wall Street Journal recently spotlighted Private Placement Life Insurance (PPLI), describing it as a “Roth IRA on steroids” for wealthy Americans seeking tax-free growth. While the headline captures the imagination, PPLI is not a loophole or an aggressive tax shelter. In the eyes of the tax code, it is a variable universal life (VUL) insurance contract designed for Qualified Purchasers and Accredited Investors. It replaces the high-commission, off-the-shelf retail product with an institutionally priced, insurance wrapper that can invest in almost any asset class but is primarily used for tax-inefficient alternative assets.
Dolly Parton Didn’t Miss Billionaire Status. She Gave It Away.
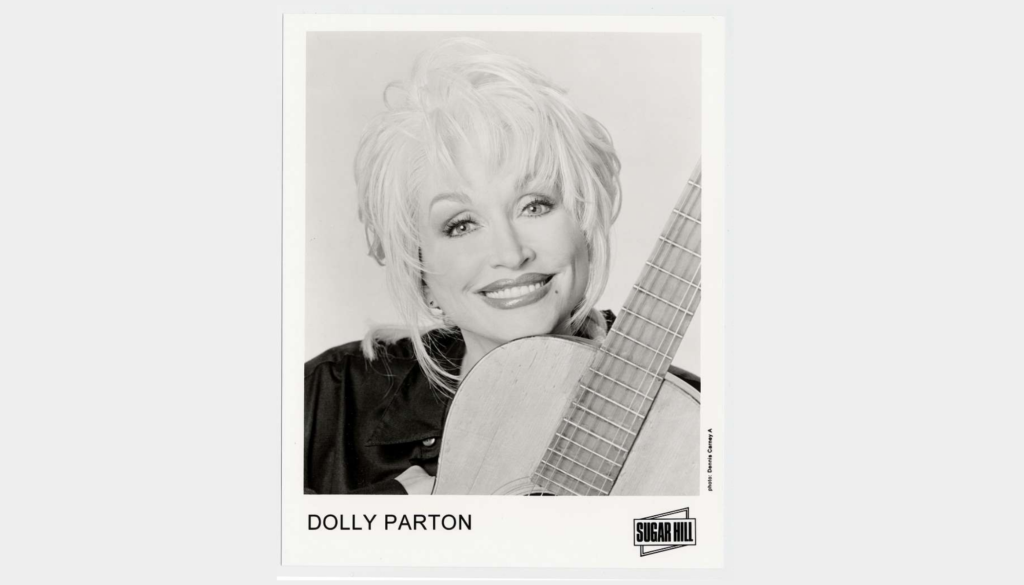
Dolly Parton died this week at 80, and American music lost one of its most beloved figures. Before the tributes fade, it is worth pausing on something she was almost as well known for as her songwriting: the money she made, the deliberate way she held onto it, and the substantial sums she chose to give away rather than bank.
Before Your Client Funds a Trump Account, Ask Them ‘Why’
Before funding a Trump Account, families should evaluate their broader gifting goals. Learn how Trump Accounts compare with 529 plans, custodial accounts, and brokerage strategies.
Choosing a Corporate Trustee: Why Separation of Duties Can Protect Your Family
One of the more important decisions when setting up a trust is deciding who will actually administer it. Sometimes a family member is well suited to the role, but if not, there are reasons to consider a corporate trustee instead: no relative able or willing to take it on, complex assets that call for professional management, concern about future incapacity, or a blended family where a neutral party can help reduce friction. A corporate trustee is simply an institution, not an individual, that takes on the legal responsibility of managing a trust’s assets and carrying out its terms.
Is Your Equity Comp Getting a Fair Look?

More and more workers are benefiting from equity compensation, and it’s not just limited to the C-suite and senior executives. Mid-level employees often accumulate meaningful positions in their company’s stock. Many of these employees rarely receive guidance on what to do with this compensation, including potential concentration risks and tax implications. Those with options often […]